

 Follow us
Tata Motors CV sales cross 200,000 units in H1 FY2027, industry sales grow 24% on strong demand
Riding on demand emanating from infrastructure development, freight movement, replacement demand of older trucks and buses, and logistics fleet expansion, commercial vehicle OEMs sold 574,255 units in April-September. While market leader Tata Motors topped the M&HCV segment, Force Motors led in small buses and M&M ruled the small goods carrier business.
 1 Views


The Indian commercial vehicle industry is in good nick this fiscal. With wholesales of 574,255 units in April-September 2026, the 17 OEMs have registered strong 24% YoY growth (H1 FY2026: 464,023 units). This is 53% of the record 10,79,871 CVs the segment sold in FY2026.
Leading the charge is market leader Tata Motors which, like the rest of the OEMs barring two, is benefiting from the considerable spend on infrastructure development across India, strong freight movement, replacement demand of older trucks and buses and logistics fleet expansion.
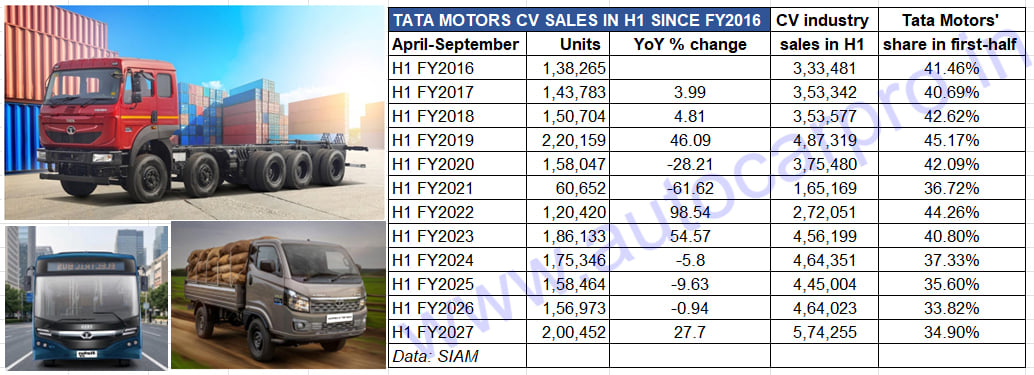 Tata Motors, with 200,452 units in H1 FY2027, crossed 200,000 sales for the second time in the first half of a fiscal. The first instance was in H1 FY2019 (220,159 units) when it commanded a 45% share.
As the SIAM-sourced sales table for H1 FY2027 (at the bottom of this analysis) depicts, Tata Motors sold 200,452 CVs in the past six months which constitutes 28% YoY growth (H1 FY2026: 156,973 units). This gives the company a 35% market share versus 34% in the year-ago period.
This also marks Tata Motors’ second-highest first-half sales after the 220,159 units it had sold in H1 FY2019 when it commanded a 45% share of the overall CV market.
While Q1 FY2027 (April-June 2026) sales at 92,561 units were a 25% increase (Q1 FY2026: 74,042 units), Q2 FY2027 (July-September 2026: 107,891 units) marked 30% YoY growth and 17% month-on-month growth.
Commenting on the Q2 numbers in the company press note, Girish Wagh, MD and CEO, Tata Motors, said: “HCVs benefited from continued activity in core sectors, sustained infrastructure, construction and mining activity; ILMCVs from e-commerce and FMCG, FMCD, and two-wheeler logistics; and SCVPU from consumption-led freight movements. Passenger transportation also maintained momentum, supported by last-mile mobility, government orders and growing intercity travel. Overall fleet utilisation levels were stable, indicating healthy underlying freight activity. Looking ahead, commodity costs remain a significant concern, while diesel prices, potential interest rate hikes and global uncertainties remain key monitorables. While the high H2 base could moderate growth rates, industry fundamentals remain supportive. Sustained government capital expenditure, a post-monsoon pickup in mining and construction activity, rising e-commerce volumes and the festive season are expected to support freight and transportation demand.”
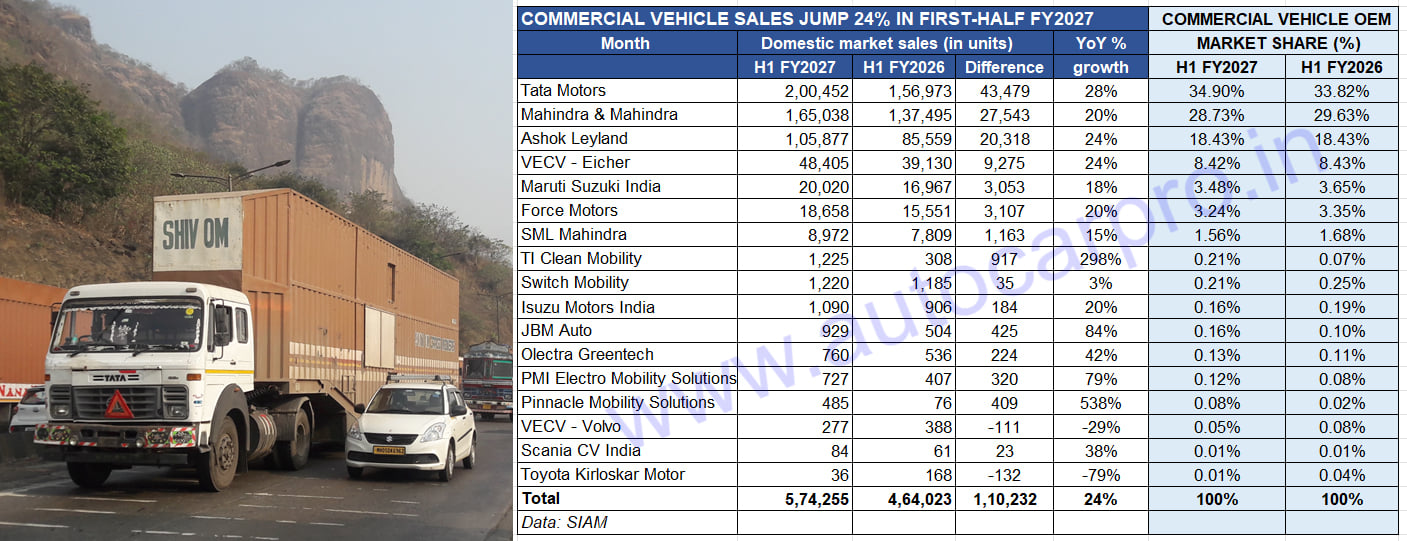 Halfway into FY2027, the 574,255 CVs sold by 17 OEMs are 53% of the record 10,79,871 CVs sold in FY2026. Demand for electric buses and goods carriers is also on the upswing.
TATA TOPS IN HEAVY BUSES & GOODS CARRIERS, FORCE MOTORS IN SMALL BUSES, M&M IN SCVs
The CV industry is essentially made up of passenger carriers (people-transporting buses and vans) and goods carriers. Each are further categorised into M&HCVs (Medium & Heavy Commercial Vehicles) and LCVs (Light Commercial Vehicles).
While Tata Motors is the CV market leader, its main competition in overall volume terms comes from Ashok Leyland in M&HCVs (buses and heavy goods carriers) as well as LCVs (buses) and from Mahindra & Mahindra in LCVs (goods carriers in the form of small CVs).
While M&HCVs accounted for 217,442 units and a 38% share of the 574,255 CVs sold in India in first-half FY2027, LCVs with 356,813 units had a 62% share. The M&HCV (heavy passenger vehicle / buses) segment registered sales of 36,163 units in H1 FY2027, up 11% YoY.
Tata Motors tops here with 11,096 units, up 13% YoY and a 31% share in this category. Ashok Leyland is the No. 2 OEM here with 9,963 units, down 5%, and a 28% share. SML Mahindra is a distant No. 3 with 2,600 units, down 4% YoY.
The big boost for M&HCV sales has come from the heavy goods vehicle category – the 181,279 units are a 30% YoY increase (H1 FY202: 139,882 units) with Tata Motors leading with 89,057 units (up 29%) and a commanding 49% share of sales in H1 FY2027, up from 38% in H1 FY2026.
Ashok Leyland (55,669 units) posted 33% YoY growth and increased its share to 33% from 30% a year ago. In third place is VECV Eicher (30,252 units, up 24%) with a 17% share of the HCV goods carriers. While M&M (4170 units, up 39%) is ranked fourth, SML Mahindra (1,373 units, up 37%) checks in at fifth position.
The LCV segment’s small buses category, which posted sales of 38,849 units, up 21%, is led by Force Motors (17,137 units, up 17%) with a commanding 49% share. Tata Motors is the No. 2 player here with 9,021 units, up 28% YoY, and a 26% segment share.
SML Mahindra takes third rank with 4,093 units, up 43% YoY, and is followed by parent M&M (2,500 units, up 26%).
The LCV goods carrier category has the largest number of OEMs: 12. The 321,964 units sold in H1 FY2027 were a 22% YoY increase, powered by this sub-segment’s leader Mahindra & Mahindra. M&M sold 158,368 small LCVs / SCVs, up 20% YoY, which gives it a 49% share including 110,991 Bolero pickups.
Tata Motors (91,278 units, up 28%) is ranked second with a 28% share. Ashok Leyland with 39,562 units including 33,998 Dost SCVs (up 21%) is third and Maruti Suzuki (20,020 units, up 18%) is fourth.
The Murugappa Group’s TI Clean Mobility sold 811 units of its Eviator E350L, up 292% YoY (H1 FY2026: 211 units), which reflects the growing demand for electric goods carriers which other OEMs are also tapping.

RELATED ARTICLES

Tata Altroz Drives Past 350,000 Sales, Contributes 34% to Tata Car Sales Since Launch
 Ajit Dalvi
 25 Oct 2026
Tata Motors’ Altroz has crossed 350,000 domestic sales since its January 2020 launch, with FY2024 marking its peak at 70...


Motorcycle OEMs clock second-highest H1 sales of 6.92 million, Hero and Honda up 12%, Bajaj down 7%
Ajit Dalvi
23 Oct 2026
Riding on best-ever monthly 1.41 million units in September, H1 FY2027’s 6.92 million are the next best after H1 FY2019’...

Maruti Suzuki’s SUV, MPV share of PV sales at 42% in H1 FY2027 with 455,692 units
Ajit Dalvi
21 Oct 2026
Utility vehicle market leader’s nine-model portfolio scales a new high for the first half of a fiscal and places it on t...